ESTATE PLANNING ATTORNEY · AKRON, OH
Irrevocable Life Insurance Trusts in Akron, OH
Spatz Law Group sets up irrevocable life insurance trusts, often called ILITs, for families across Akron and Northeast Ohio, so a large policy pays out to your family without adding to your taxable estate.
A life insurance payout that pushes your estate over the limit
Most people think of life insurance as separate from their estate. For tax purposes, it isn't. If you own the policy, the full death benefit counts toward your taxable estate, and a large policy added to your home, retirement accounts and business can push the total higher than you expect. An irrevocable life insurance trust owns the policy instead, so the payout goes to your family without being counted in your estate. Ohio has no estate tax, so this is about federal tax only. In 2026, the federal exemption is $15 million per person, or $30 million for a married couple, so an ILIT's tax benefit matters mainly for larger estates or those likely to grow past that line.
Controlling how the money is used after you're gone
A large check handed to a grieving spouse or a 22-year-old can disappear quickly. With the policy inside a trust, the trustee you choose follows your instructions: paying for college, supporting your spouse, or releasing money to your children in stages. The trust can also keep the money protected from a child's future divorce or creditors.
Keeping the trust working year after year
An insurance trust needs a little upkeep. Each year you give the trust money to pay the premium, and the beneficiaries are notified of their right to withdraw it, which lets the gift qualify for the annual gift tax exclusion. Your trustee is shown exactly how this works, so the paperwork is done right and the policy stays in force.
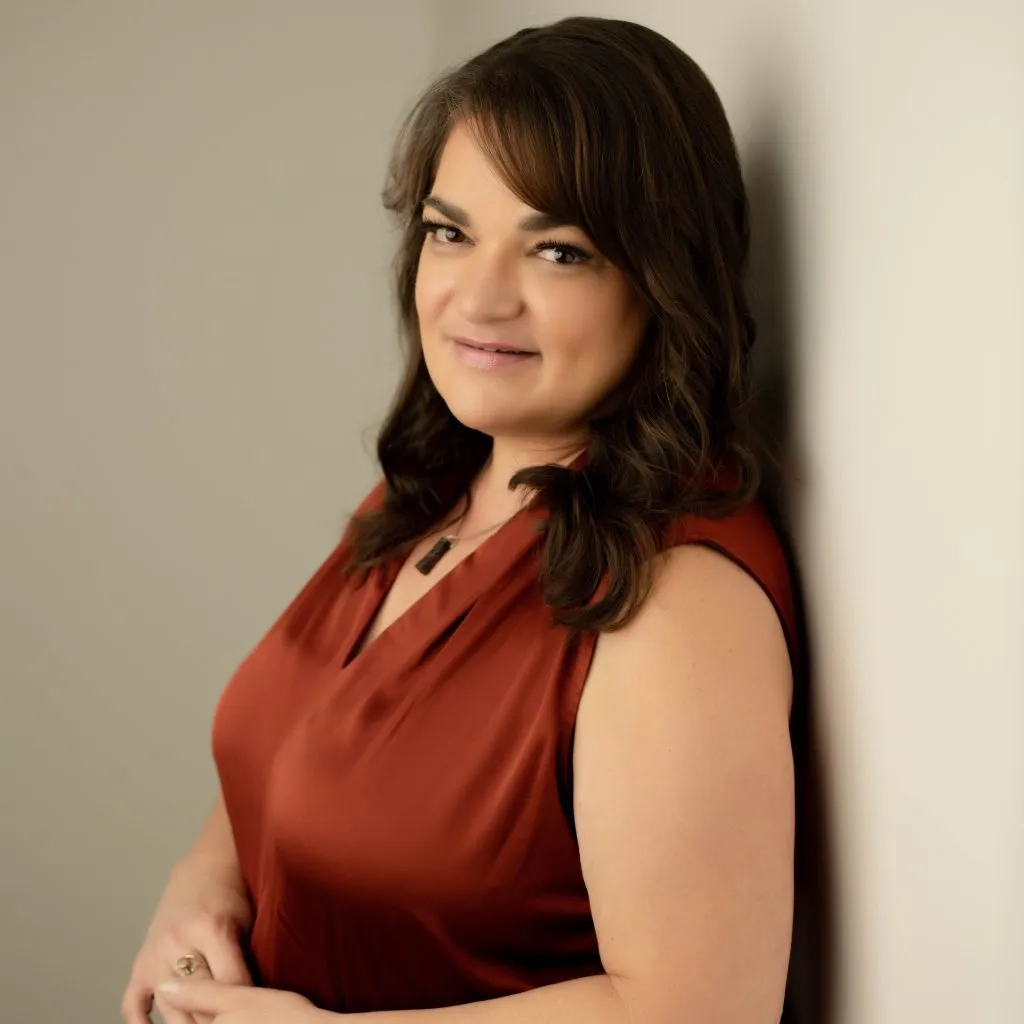
Your attorney
Debra A. Spatz
Licensed in Ohio since 2008 · Ohio Supreme Court Reg. #0083356
Chicago-Kent College of Law · University of Illinois, Finance
Meet DebraBefore your first conversation
Bring your current life insurance policies, including the owner, beneficiary and death benefit for each, and a rough list of what else you own. If you're shopping for a new policy, bring the quote.
★★★★★Google review
If you are looking for a local estate attorney in Bath, Ohio, Deb Spatz with Spatz Law Group is truly exceptional. I know several people who have worked with Deb, and they consistently share nothing but positive experiences. Deb takes the time to get to know you and your story, allowing her to create a plan that brings real peace of mind for you and your family. She even offers the option to record a legacy video for your loved ones, which is an incredibly meaningful and lasting gift. Do not wait until it is too late. I highly recommend calling Deb today.
Frequently Asked Questions
Do I need an ILIT, or can my revocable trust be the beneficiary?
For most families, naming your revocable trust as the beneficiary of your life insurance does the main job: the payout goes to a trustee you choose and is released on your schedule, not handed to a child at 18. An ILIT adds two things a revocable trust can't: it keeps the payout out of your taxable estate, and it can offer stronger protection from creditors. If your estate is well under the federal exemption, you may not need one. Debra tells you plainly which fits.
Can I put an existing policy into the trust, or should the trust buy a new one?
Both are possible. Transferring an existing policy works, but if you die soon after the transfer, the payout can still count in your estate. When a new policy is needed anyway, having the trust apply for it from the start avoids that waiting period.
Who pays the premiums on a policy owned by the trust?
You do, indirectly. Each year you give the trust enough money to cover the premium, and the trustee pays the insurance company. Those gifts usually fit within the annual gift tax exclusion, which is $19,000 per beneficiary in 2026.
Can my spouse be the trustee?
Often, yes, though the trustee's powers need to be drafted carefully so the policy stays outside both of your estates. The insured person should never be the trustee. Debra explains the options and helps you choose who should serve.
Can I change the beneficiaries later?
Not directly, because the trust is irrevocable. But the trust can be written with some flexibility built in, such as giving a trusted person limited power to adjust it as your family changes. That flexibility is easiest to include at the start.
What kind of life insurance works best in this trust?
Usually permanent insurance, like whole life or universal life, since the goal is a payout whenever death occurs. Married couples often use a second-to-die policy that pays after both spouses pass, when estate tax would come due.